Market analysis
How to read the Commitments of Traders report
The CFTC Commitments of Traders (COT) report breaks down open interest by trader category. Read the position date first, choose a consistent report format, then compare long and short positions separately before interpreting the net figure.
Tuesday positions, usually a Friday release
COT is a delayed positioning snapshot. The CFTC generally publishes it at 3:30 p.m. Eastern Time on Friday, covering positions held at the close of the preceding Tuesday. It does not show the positions traders hold at the moment you download it.
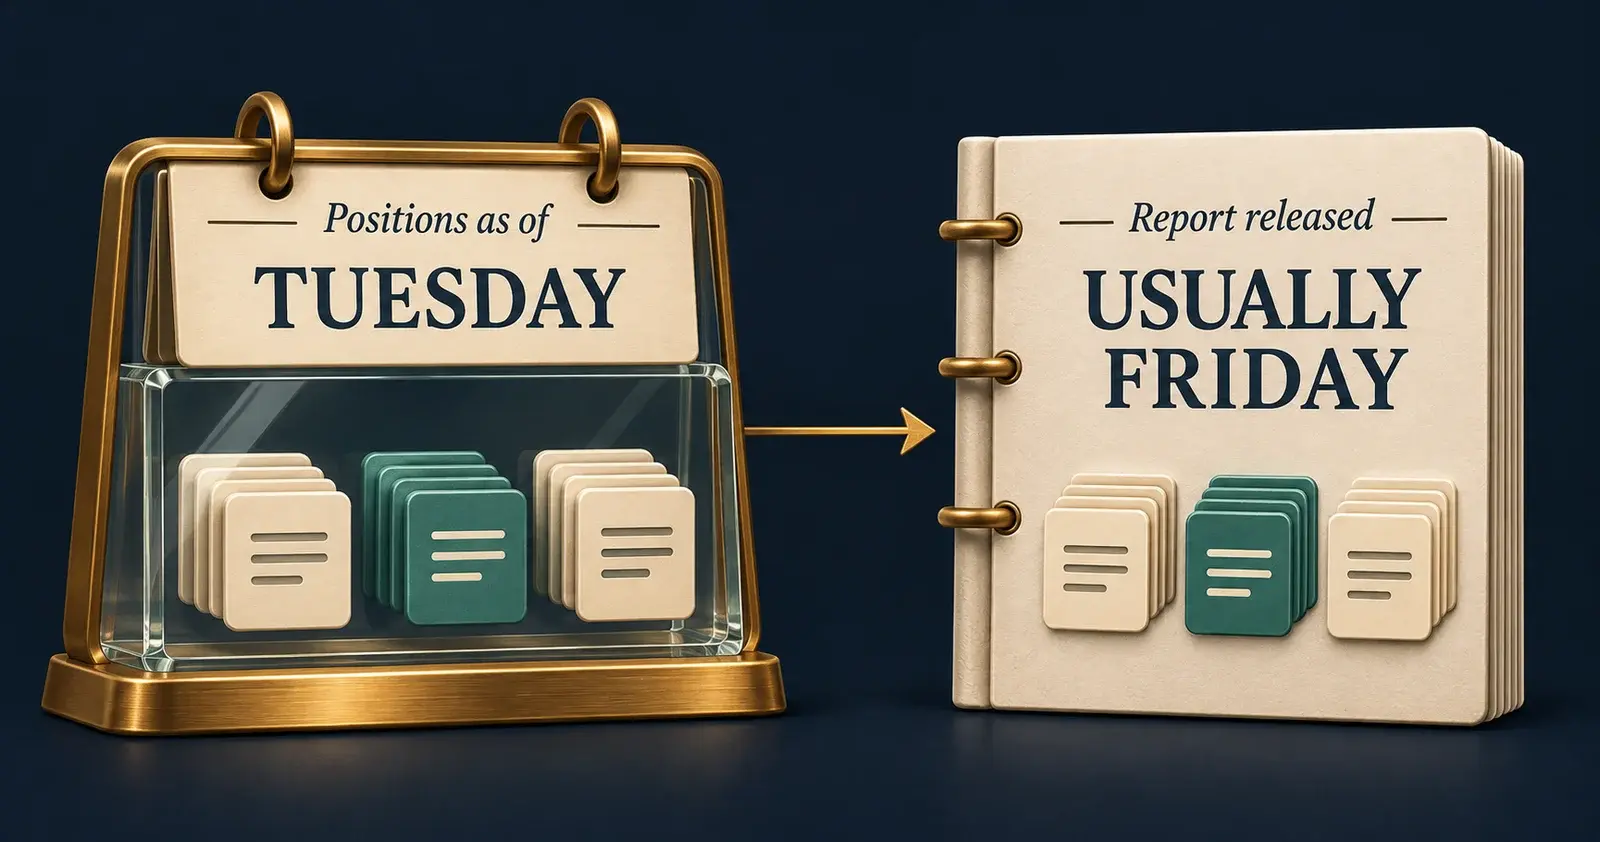
Read the “as of” date inside the report, rather than using the download date as the observation date. Holidays can delay publication; the CFTC release calendar identifies those exceptions. For a week-to-week comparison, retain both position dates so a delayed release does not look like an extra observation.
Sources: CFTC Commitments of Traders: report types and release timing · CFTC Commitments of Traders release schedule
Choose the report family and contract scope
Start with the market name and exchange, then select the report family below. Legacy, Disaggregated and Traders in Financial Futures reports are available in futures-only and futures-and-options-combined versions. The categories describe types of traders, not a ranking of forecasting skill.
| Report | Coverage and reportable trader categories |
|---|---|
| Legacy | Broad market coverage: Commercial and Noncommercial. |
| Disaggregated | Agricultural and other physical commodity markets: Producer/Merchant/Processor/User, Swap Dealers, Managed Money and Other Reportables. |
| Traders in Financial Futures (TFF) | Financial contracts, including currencies, Treasuries and stock indexes: Dealer/Intermediary, Asset Manager/Institutional, Leveraged Funds and Other Reportables. |
| Supplemental | 13 selected agricultural contracts, futures and options combined: Commercial, Noncommercial and Index Traders. |
Sources: CFTC Commitments of Traders: report types and release timing · CFTC Disaggregated Commitments of Traders explanatory notes · CFTC Traders in Financial Futures explanatory notes
Keep the columns comparable
Futures-only reports count futures positions. Combined reports convert options into futures-equivalent positions using delta before adding them to futures. A combined short figure can therefore include the short-equivalent exposure of puts; it is not simply a count of short futures contracts. Do not compare a futures-only observation with a combined observation and call the difference a weekly position change.
The “All” total combines the commodity’s contract months, rather than isolating the front month. Some long-form reports also show “Old” and “Other” crop-year subsets. Preserve that scope, along with the same market, report family, units and futures/options selection, in your history.
“Nonreportable” is the remainder after reportable positions are subtracted from total open interest on each side. It is not a verified category of retail traders. The CFTC does not know the commercial or noncommercial classification of those nonreportable traders. Likewise, a reportable trader’s business classification does not identify the purpose of every individual position.
Sources: CFTC Commitments of Traders explanatory notes · CFTC Disaggregated Commitments of Traders explanatory notes · CFTC Traders in Financial Futures explanatory notes
A larger net long does not require more longs
Within one category, net positioning is long positions minus short positions. This hypothetical futures-only example keeps the category and market unchanged:
- The net long increased by 15,000 contracts, but reported longs did not increase. The change came entirely from the smaller reported short position.
- Position changes are not an order-by-order trading record. Category membership can also change, so the report alone cannot establish that an unchanged set of traders bought to close exactly 15,000 shorts.
- Every outstanding futures contract has a long and a short side. One category’s net long does not mean the whole market has more long contracts than short contracts.
| Position date | Long | Short | Net long |
|---|---|---|---|
| Earlier Tuesday | 100,000 | 80,000 | 20,000 |
| Following Tuesday | 100,000 | 65,000 | 35,000 |
| Change | 0 | −15,000 | +15,000 |
Sources: CFTC Commitments of Traders explanatory notes · CFTC Disaggregated Commitments of Traders explanatory notes · CFTC Traders in Financial Futures explanatory notes
Read spreading without counting it as directional exposure
In the Legacy futures-only report, a noncommercial trader with 300 long and 200 short contracts in the same commodity would contribute 100 to the Long column and 200 to Spreading. The 200 offsetting contracts belong on both sides when reconciling that trader’s total long and short positions; they are not an additional 200-contract directional bet.
Spreading treatment and available columns depend on the report. For example, Disaggregated reports do not show a separate spreading column for Producer/Merchant/Processor/User positions. Use the notes for the exact format instead of copying a Legacy column formula into every report.
The net-position example can help describe how a group’s reported exposure changed. It cannot tell you that prices must rise, that the group still holds that exposure today, or that a futures price move was caused by those positions. For a current trade decision, COT supplies historical positioning context, not a live order-flow signal.
Sources: CFTC Commitments of Traders explanatory notes · CFTC Disaggregated Commitments of Traders explanatory notes